Investor vs investee can be confusing because the two terms describe people or entities involved in the same financial transaction. They are closely connected, but they do not mean the same thing. One side puts money or capital into an investment, while the other side receives the investment or represents the entity in which the investment is held.
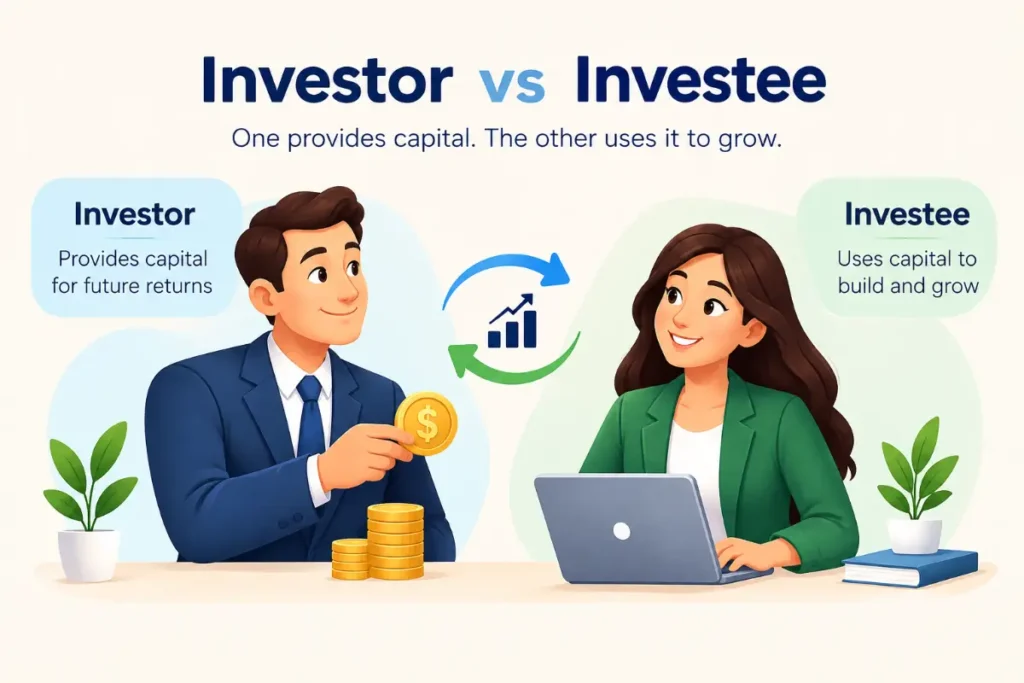
The easiest way to remember the distinction is to focus on the direction of the money. The investor is the party making the investment. The investee is the person, company, or other entity being invested in.
You will see these terms frequently in accounting, corporate finance, venture capital, private equity, investment agreements, and financial reporting. Investee is less common in everyday conversation, so it can sound unfamiliar even to people who understand investing.
This guide explains the difference in plain American English. It also covers the cost method, equity method, significant influence, common accounting terminology, practical examples, and related financial terms so you can recognize and use both words correctly.
Quick Answer
An investor is a person or organization that puts money or other resources into an investment with the goal of earning a return or achieving another financial objective. An investee is the person, company, or entity receiving the investment or serving as the investment target.
Investor And Investee Comparison
| Feature | Investor | Investee |
|---|---|---|
| Role | Makes an investment | Receives or is the subject of an investment |
| Part of speech | Noun | Noun |
| Main focus | Capital provider | Investment recipient or target |
| Typical contexts | Stocks, funds, startups, real estate | Corporate investment, accounting, equity holdings |
| Financial position | Puts capital into an opportunity | Receives capital or is owned in part |
| Common phrase | Investor relations | Investee company |
| Everyday usage | Very common | More specialized |
| Example | The investor bought shares. | The investee issued new shares. |
The simplest distinction is directional. The investor moves capital into an opportunity. The investee is on the receiving or target side of that investment relationship.
What Does Investor Mean
Investor is a noun for a person, business, fund, or other entity that commits money or capital to an asset, company, project, security, or other opportunity. The purpose is generally to earn income, preserve capital, gain value, or achieve another financial objective.
A person who buys shares of a public company is an investor. A venture capital fund that finances a startup is also an investor. A company that purchases a stake in another business can be an investor too.
The word describes the side putting capital at risk. That capital might be used to buy stocks, bonds, real estate, private company shares, or other assets.
Investors can have very different strategies. An individual may invest for retirement, while a venture capital firm may seek rapid growth from early stage companies. A pension fund may invest large amounts across many asset classes to support long term obligations.
The common element is the same. The investor commits capital with an expectation of some financial or strategic benefit.
What Does Investee Mean
Investee is a noun used in finance and accounting for the person or entity in which an investment is made. In many business contexts, the investee is the company that receives investment capital or the entity whose ownership interest is held by an investor.
For example, if ABC Capital buys 30 percent of XYZ Inc., ABC Capital is the investor and XYZ Inc. is the investee.
Investee is less common in everyday conversation than investor. You are more likely to see it in financial statements, accounting guidance, investment agreements, corporate reports, and discussions about ownership interests.
The word is particularly useful when professionals need to describe two sides of an investment relationship precisely. Instead of repeatedly saying “the company receiving the investment,” an accounting professional can simply use investee.
The term does not automatically mean that the investor controls the company. An investment may represent a small ownership interest, a significant minority interest, or another type of financial relationship.
How The Two Roles Work Together
These terms describe two sides of the same financial relationship. Imagine that a private equity firm purchases an ownership interest in a manufacturing company. The private equity firm is the investor because it commits capital. The manufacturing company is the investee because it is the business in which the investment is made.
The relationship can become more complicated when an investment is made through several entities. A parent company may invest through a subsidiary, a fund may invest in several portfolio companies, and multiple investors may own different percentages of one investee.
The basic vocabulary does not change. The party making the investment is the investor. The entity receiving or being invested in is the investee.
A useful mental model is:
Investor → Investment → Investee
This is not an accounting formula. It is simply a quick way to understand the relationship.
When discussing the duration of an investment or the point at which an agreement ends, it helps to know how to use “until” correctly so your writing remains clear and grammatically accurate.
Cost Method And Equity Method
The difference between investor and investee becomes especially important in accounting. When a company holds an ownership interest in another entity, the accounting treatment can depend on the nature and extent of the relationship.
Under the cost method, an investment is generally carried based on the investor’s recorded investment amount subject to applicable accounting requirements. The equity method takes a different approach by adjusting the carrying amount for the investor’s share of certain changes in the investee’s net assets and results.
The important point is that the investor and investee are not names for two accounting methods. They identify the parties in the relationship. Cost method and equity method describe approaches to accounting for an investment.
For US financial reporting, the equity method is closely associated with accounting for investments when an investor has significant influence over an investee. The precise accounting requirements depend on the facts and the applicable accounting framework.
This distinction is important for students and professionals because accounting terminology can make a basic investment relationship appear more complicated than it is. First identify who invested and who was invested in. Then determine which accounting rules apply.
Significant Influence In Accounting
Significant influence is an important concept when discussing investments in companies. It generally means that an investor can exercise meaningful influence over the operating or financial decisions of another entity without controlling it.
This distinction matters because an investment that gives an investor significant influence may receive different accounting treatment from a passive investment.
In US GAAP, the equity method guidance is addressed in ASC 323. The investee remains the company in which the investment is held, while the investor is the entity holding the investment.
A common example is an investor owning a meaningful minority interest in another company and having representation or participation that gives it influence over important decisions. Ownership percentage can be an important indicator, but accounting conclusions require consideration of the overall facts and circumstances.
Significant influence is therefore about more than simply asking how much stock someone owns. Governance rights, board representation, participation in policy decisions, and other circumstances can matter.
Investor And Investee In Equity Method Accounting
Under the equity method, the investor generally recognizes its share of the investee’s earnings or losses in accordance with the applicable accounting rules. The investment balance is adjusted for relevant changes in the investor’s share of the investee’s net assets.
For example, suppose Company A invests in Company B and applies the equity method. Company A is the investor and Company B is the investee.
If Company B reports income, Company A may recognize its proportionate share of that income under the equity method. If Company B reports a loss, Company A may recognize its share of the loss subject to the applicable rules.
The terminology is straightforward even when the accounting becomes technical.
The investor owns or holds the investment. The investee is the entity whose results and net assets may affect the investment accounting.
Examples In Sentences
Investor Examples
- The investor purchased shares in the technology company.
- The investor reviewed the company’s financial statements before committing capital.
- Several investors participated in the funding round.
- The investor expects the project to generate a return over time.
- The fund became a major investor in the startup.
- The investor asked management about future growth plans.
- A private equity investor acquired a minority interest in the business.
- The investor received dividends from the shares.
- The company is seeking an investor for its expansion.
- Each investor must review the risks before making a decision.
These examples show that investor can describe individuals, funds, companies, and other organizations. The term does not identify a particular investment strategy.
Investee Examples
- The investee reported higher revenue during the year.
- The investor requested additional information from the investee.
- The investee issued new shares as part of the financing.
- The accounting team reviewed the investee’s financial results.
- The investor holds a significant interest in the investee.
- The investee operates in several international markets.
- Management discussed the transaction with the investee.
- The investee company provided its quarterly financial information.
- The investor analyzed the investee’s business before completing the transaction.
- The agreement explains the rights of the investor and the obligations of the investee.
These sentences reflect professional usage. In casual conversation, people often replace investee with company, business, startup, or investment target because those words are more familiar.
Common Mistakes
A frequent mistake is treating investor and investee as interchangeable. They are not. The first identifies the party making the investment, while the second identifies the party receiving or representing the investment target.
- Incorrect: The investee purchased shares in the startup.
- Correct: The investor purchased shares in the startup.
If the startup received the capital, it would be the investee.
Another common mistake is assuming that investee always means a company receiving cash directly. In accounting discussions, the term can describe an entity in which an investor has an investment, including situations involving ownership interests and equity method accounting.
Writers also sometimes confuse investee with employee or appointee because of the ending. The suffix pattern does not make the words interchangeable. Investee is tied specifically to the verb invest and describes the recipient or target of an investment relationship.
Confusing The Two Directions
One reliable way to avoid the mistake is to ask a simple question:
Who put the money into the investment?
That party is the investor.
Then ask:
Which entity received the investment or is the investment held in?
That entity is the investee.
This works particularly well when reading accounting problems. Identify the parties first, then analyze the accounting treatment.
Confusing Investee With Borrower
An investee should not automatically be treated as a borrower. A borrower receives a loan and normally has an obligation to repay the borrowed amount according to the loan agreement.
An investee may receive equity capital instead. In an equity investment, the investor acquires an ownership interest rather than simply lending money.
The distinction matters because debt and equity create different financial relationships.
An investor and investee may have different levels of influence, responsibility, or financial exposure, creating an understanding of imbalance that can affect how their relationship works.
Investor And Investee In Financial Statements
Financial reporting often uses these terms because the relationship between two entities can affect how an investment appears in the financial statements.
The investor’s accounting records may contain an investment asset. Depending on the applicable accounting model, the investor may recognize income, losses, dividends, changes in carrying value, or other adjustments associated with the investment.
The investee prepares its own financial statements and reports its assets, liabilities, equity, revenue, expenses, and other relevant information.
This creates two different reporting perspectives. One company is reporting its investment. The other company is reporting the underlying business and its own financial position.
That distinction helps explain why accounting discussions often use investor and investee together.
The same transaction can therefore appear differently from each company’s perspective. A student who keeps the two perspectives separate will usually find the accounting terminology much easier to understand.
Investor And Investee In Venture Capital
Venture capital provides a clear example of the relationship. A venture capital fund invests money in an early stage company in exchange for an ownership interest or another financial arrangement.
The fund is the investor. The startup is the investee.
The investor may evaluate the startup’s management team, market, financial performance, technology, growth prospects, and risks before investing. The investee may use the capital to hire employees, develop products, expand into new markets, or strengthen its operations.
Multiple investors can invest in the same startup. In that situation, each participating fund or person can be an investor, while the startup remains the investee.
The relationship can also change over time. A startup may have several financing rounds, bringing in new investors while retaining earlier investors. Each investor has its own investment relationship with the company.
Investor And Investee In Private Equity
Private equity transactions can involve a similar relationship, although the structure and strategy may be more complex. A private equity firm may purchase an ownership interest in an established company and work with management to increase the company’s value.
The private equity firm is the investor. The acquired or partially owned business is the investee.
Investment structures can involve holding companies, acquisition vehicles, subsidiaries, and co-investors. As a result, a single transaction may contain several layers of investor and investee relationships.
When reading a transaction document, identify the entity that is making the investment and the entity whose ownership interest is being acquired. That usually makes the terminology much easier to follow.
Investor And Investee In Stock Market Language
Public stock market discussions usually use investor much more often than investee. Someone who buys shares of a publicly traded company is commonly called an investor or shareholder.
The company issuing the shares can technically be described as the investee in certain investment and accounting contexts. However, ordinary investors are more likely to call it a company, issuer, or stock rather than use the word investee.
This is an important usage distinction. A term can be correct without being the most natural choice in everyday speech.
If you are writing a casual explanation for individual investors, company or issuer may be clearer. If you are discussing accounting relationships, investee may be the more precise term.
Investor And Investee In Contracts
Investment agreements often need precise terminology because different parties have different rights and responsibilities.
A contract might define one entity as the investor and another as the investee. It can then use those defined terms throughout the document instead of repeating long legal names.
For example, an agreement may establish requirements concerning financial reporting, information rights, ownership interests, governance, transfer restrictions, or investor protections.
The exact legal meaning depends on the contract. Writers should therefore follow the defined terms in the document rather than assuming that every agreement uses the words in precisely the same way.
Defined terms can also be capitalized in legal documents. That capitalization is a drafting convention rather than a change in the ordinary meaning of the words.
Related Financial Terms
Investor and investee belong to a larger group of financial terms that describe investment relationships.
Shareholder
A shareholder owns shares in a corporation. An investor can be a shareholder, but the terms are not identical. Someone can invest in assets that do not involve corporate shares.
Issuer
An issuer is an entity that issues securities such as stocks or bonds. A company can be both an issuer and the target of an investment.
Portfolio Company
A portfolio company is a business held as an investment by a private equity firm, venture capital fund, or another investment organization. In many contexts, a portfolio company can also be described as an investee.
Parent Company
A parent company controls another company, commonly called a subsidiary. This relationship is different from ordinary investment and can involve control rather than significant influence.
Subsidiary
A subsidiary is controlled by another entity. It should not automatically be treated as synonymous with investee because the accounting and corporate relationship can be substantially different.
Equity Interest
An equity interest represents an ownership stake in an entity. Investors may acquire equity interests in companies as part of an investment.
Significant Influence
Significant influence describes the ability to participate in important financial and operating policy decisions without necessarily controlling the entity. It is a central concept in many equity method accounting discussions.
Investor And Investee In Plain English
If accounting terminology feels complicated, reduce the relationship to two basic roles.
- The investor is the party putting capital into the opportunity.
- The investee is the entity being invested in.
For example, imagine that a company invests $5 million in a growing software business. The company providing the $5 million is the investor. The software business is the investee.
The transaction can become much more detailed when ownership percentages, voting rights, dividends, financial reporting, or significant influence enter the picture. But the vocabulary remains grounded in those two basic roles.
This simple distinction is useful when studying accounting because many textbook questions introduce several companies at once. Before calculating anything, identify which entity invested and which entity received the investment.
Which Word Should You Use
Choose investor when you are talking about the person or entity making the investment.
Choose investee when you are talking about the entity receiving the investment or the entity in which the investment is held.
A simple mental picture can help:
Investor → capital → investee
The investor puts money into the relationship. The investee receives the capital or is the entity in which the investment is made.
In ordinary financial conversations, investor is the more familiar word. Investee is more specialized and appears frequently in accounting, investment documentation, corporate finance, and professional financial analysis.
If your audience is not familiar with accounting terminology, explain investee the first time you use it. That small clarification can make technical writing much easier to understand.
Expert Language Insight
The most useful editorial distinction is between technical correctness and natural usage.
Investor is a familiar word that works comfortably in everyday financial discussions. You can use it when discussing a person buying stocks, a fund financing a startup, or a corporation acquiring an ownership interest.
Investee is more specialized. It is completely appropriate in accounting and corporate finance, but it can sound overly technical in casual writing.
For example:
The investor reviewed the investee’s financial statements.
This is natural in an accounting context. For a general audience, a clearer version might be:
The investment firm reviewed the company’s financial statements.
Neither sentence is inherently better. The right choice depends on the audience and purpose.
Experienced financial writers also avoid assuming that every investment creates an investee in exactly the same practical sense. The underlying transaction matters. Equity investments, debt arrangements, acquisitions, joint ventures, and controlled subsidiaries can involve different relationships and accounting consequences.
When writing educational material, define the terms before discussing technical rules. That prevents readers from confusing the names of the parties with the accounting methods used to report their relationship.
The most dependable shortcut remains simple: the investor invests, while the investee is invested in.
If you are describing a company or person that supplies financial services or resources, knowing the correct spelling of provider can help you avoid a common spelling mistake.
Frequently Asked Questions
What Is The Difference Between An Investor And An Investee
An investor is the person or organization making an investment. An investee is the person, company, or entity receiving the investment or serving as the investment target. For example, if a fund purchases an ownership interest in a startup, the fund is the investor and the startup is the investee.
What Is An Investee Company
An investee company is a company in which another person or organization has made an investment. The investor may hold shares, an ownership interest, or another qualifying financial interest. The term is especially common in accounting, corporate finance, investment agreements, and financial reporting.
Is The Investee The Owner
Usually, no. The investee is generally the entity in which the investor has invested. The investor may actually own part of the investee, but the word investee identifies the company or entity on the investment side rather than identifying its ownership status. Ownership depends on the structure and terms of the transaction.
What Is An Investor In Accounting
An investor is an individual or entity that holds an investment in another entity. Accounting treatment depends on the type of investment and the relationship between the parties. When significant influence exists, equity method accounting may apply under the relevant accounting framework. The investor records the investment according to the applicable rules.
What Is An Investee Under The Equity Method
Under equity method accounting, the investee is the entity in which the investor holds an investment that qualifies for equity method treatment. The investor generally recognizes its share of the investee’s earnings or losses and adjusts the investment balance for relevant changes according to applicable accounting requirements.
What Is The Cost Method
The cost method is an accounting approach used in certain circumstances to account for an investment based on the applicable recorded investment amount, subject to relevant accounting requirements. It should not be confused with the terms investor and investee. Investor identifies the investing party, while investee identifies the entity associated with the investment.
What Does Significant Influence Mean
Significant influence generally means that an investor can participate meaningfully in the financial and operating policy decisions of another entity without controlling that entity. It is an important concept in determining accounting treatment for certain investments. The assessment depends on the facts and circumstances and the applicable accounting framework.
Is Investee A Common Word
Investee is a legitimate financial and accounting term, but it is less common in everyday English than investor. Financial professionals frequently use it when discussing investments, ownership interests, equity method accounting, and corporate relationships. In casual writing, company, business, or investment target may sometimes sound more natural.
Conclusion
The difference between investor and investee is simple once you identify the direction of the investment. The investor puts capital into an opportunity, while the investee is the person or entity receiving the investment or serving as the investment target.
The distinction becomes especially important in corporate finance and accounting, where the relationship can affect financial reporting and the treatment of an investment. Terms such as equity method, cost method, significant influence, shareholder, issuer, and portfolio company describe related concepts but do not replace the basic roles.
For everyday writing, remember the simplest rule: the investor invests, and the investee is invested in. That mental shortcut makes the terminology much easier to understand and use correctly.